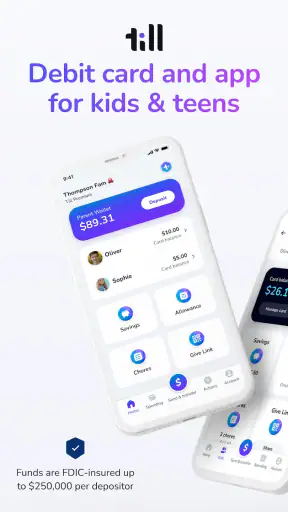
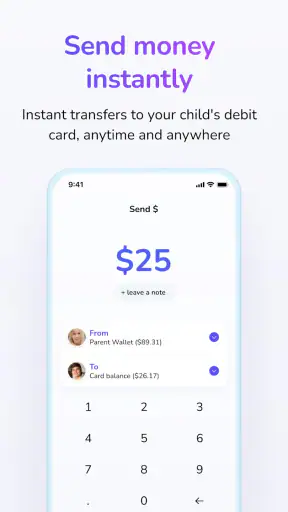
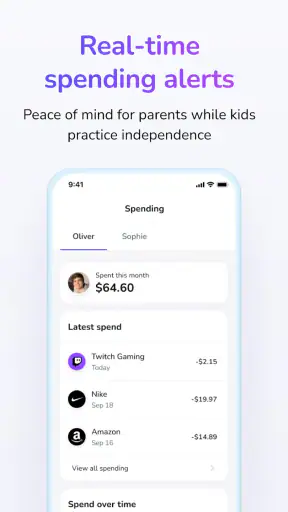
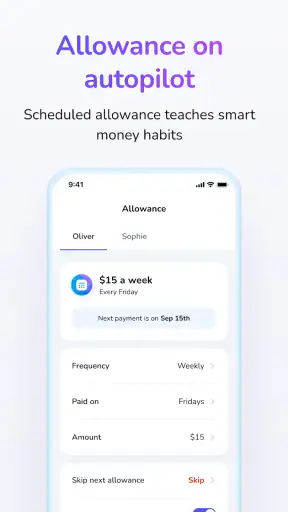
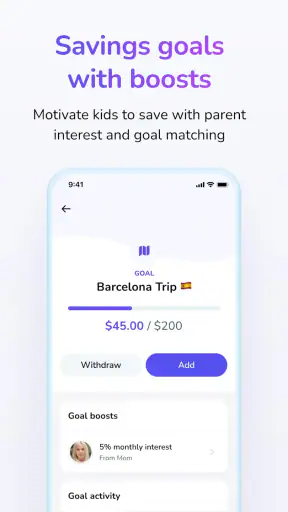
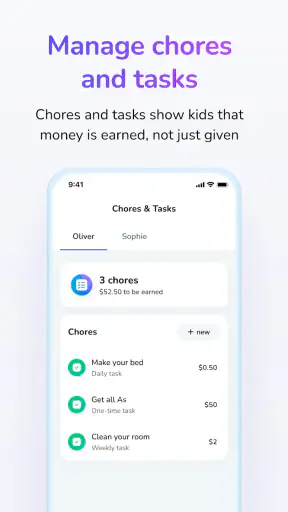
When I look at a finance app for children, I do not judge it only by whether it provides a card. I want to know how clearly the family can make decisions, where the parent remains involved, and whether the app encourages useful money habits instead of turning spending into a game. Till: Debit Card for Kids takes that family-learning approach, pairing a debit card with an app designed for children and teenagers who are beginning to manage their own spending.
I reviewed it as a practical household tool rather than as a replacement for a full banking service. That distinction matters. Till is aimed at a parent who wants to introduce controlled independence, not at an adult looking for investments, complex budgeting, or a complete everyday bank account. Its focus is narrower, and in my experience that can be a strength when the goal is to help a young person understand the consequences of ordinary purchases.
The app is free to install, although in-app purchases range from $7.99 to $79.00 per item. It is made by Till Financial, belongs in the finance category, and is suitable for Everyone. The Android release requires Android 7.0 or later. Those details make it accessible to many families, but they also mean I would read the available purchase choices carefully before treating the free download as the full cost of using the service.
Trust starts with the parent-child relationship
The strongest reason to consider Till is that it puts a supervised transition between parental control and a child’s first independent spending decisions. A conventional debit card can give a teenager access to money without creating much space for discussion. Cash can be simple, but it leaves no convenient shared record inside a family workflow. Till sits between those approaches: the young person gets a card and an app, while the parent can remain part of the process.
That arrangement is useful for a child who is ready to make small choices but still needs boundaries. I can imagine using it for school lunches, occasional treats, a birthday gift, or a planned allowance. The important point is not the card itself. The useful part is having a concrete moment after a purchase when parent and child can talk about what happened, whether it was expected, and how the next decision might change.
I would not describe this as a tool that automatically teaches financial responsibility. No app can do that on its own. A child can still spend carelessly, misunderstand a balance, or treat available money as an invitation to use it immediately. Till is more valuable when a parent uses it as a prompt for regular conversations. Without that involvement, it risks becoming just another payment method with a youthful design.
The app has attracted a 4.5 average from around 2.2 thousand ratings, with more than 100 thousand installs. That level of adoption suggests it is not an obscure experiment, but popularity should not be confused with a guarantee that it fits every household. Families differ in how much oversight they want, how they handle allowances, and whether they are comfortable giving a child access to a payment card at all.
What the app is really good at
Its clearest use case is staged independence. I would start with a specific purpose rather than handing over unrestricted spending responsibility. For example, a parent might decide that the child can use the card for a weekly school-food budget while keeping other purchases as a conversation requiring approval outside the normal routine. This turns the app into a learning exercise: the child has freedom within a defined area, and the parent can review the result with them.
A second useful scenario is preparing a teenager for a move toward adult banking. Instead of waiting until the first job or college experience to explain balances and spending, a family can use everyday purchases as practice. The teenager learns that money is finite, that a declined or restricted transaction has a reason, and that a balance reflects previous decisions. Those lessons are more memorable when they happen around a real purchase than when they are presented as a worksheet.
I also see value for separated households or families where allowance discussions become inconsistent. A shared app-based routine can give everyone a clearer reference point, provided the adults agree on the rules and the child understands them. That is not a special feature I would assume automatically; it is a workflow a family can create around the app. The benefit comes from consistency, not from the software replacing communication.
Controls matter more than colorful presentation
For a children’s finance product, trust depends on visible account controls and understandable choices. I would pay close attention during setup to which adult manages the account, how money reaches the child’s spending balance, and what actions require parental involvement. I would also look for clear explanations before confirming any paid option or changing a setting. Those are the moments when user agency matters most.
A good family workflow should make it obvious who is responsible for the money and who is allowed to spend it. If a child sees a balance, that balance should be discussed as a limit with a purpose, not as an endless source of funds. I recommend agreeing on three things before the card is used: what the money is for, what happens when it runs out, and how the family will review purchases. Writing those rules down in ordinary language can prevent arguments later.
One practical tip is to begin with a small, predictable amount and a short review cycle. A weekly conversation is easier for a younger child than a vague promise to “check the account sometime.” Ask the child to explain one purchase, one choice they postponed, and what they would do differently next time. This makes the app part of a learning loop rather than a silent monitoring system.
Another tip is to separate spending lessons from punishment. If a teenager uses the card for something unexpected, I would first ask what they thought the rule was. Confusion and deliberate rule-breaking need different responses. The app can show the financial consequence, but the parent still has to decide how to teach from it. That human judgment is one of the product’s limits and also one of its most important safeguards.
Data-sensitive moments deserve a deliberate pause
Finance apps handle information that deserves more attention than a typical entertainment download. When installing Till, I would not rush through account creation or payment-related screens. I would read every permission and privacy explanation shown in the app and in the operating system, especially when the app asks for access that is not obviously needed for the task at hand. I would also make sure both the adult and child understand which device is signed in.
I cannot treat a family-friendly purpose as proof that every data practice is automatically comfortable for every household. Parents should make their own decision after reviewing the current privacy notices and the choices presented during setup. The right question is not simply “Is this app for kids?” but “Do I understand what information I am entering, why it is needed, and which choices I can change later?”
There are several moments when I would slow down: creating the adult account, connecting a funding method, adding a child, confirming a purchase option, and signing in on a shared phone. I would avoid saving credentials on a device that children or visitors use casually. I would also keep system updates enabled and use the device’s normal lock and account-security tools. These are ordinary precautions, but they matter more when an app is connected to spending.
Parents should also discuss notifications. A child may interpret a payment alert as a judgment, while an adult may treat it as a useful safety check. Agreeing on how alerts will be handled can reduce embarrassment and encourage honest conversations. If every notification leads to an angry reaction, the child may learn to hide mistakes rather than understand them. If alerts are ignored completely, the family loses one of the app’s practical teaching opportunities.
How it compares with cash and ordinary bank cards
Cash remains better for families that want the simplest possible lesson. A child can see the money physically disappear, and there is no account setup or digital sign-in to manage. Cash is also useful when a parent wants to give a fixed amount for a specific outing. The trade-off is that it offers less convenient visibility after the money changes hands, and it does not resemble the payment habits a teenager will soon encounter in daily life.
An ordinary bank debit card may be the better choice for an older teenager who already understands balances, transaction records, and basic account security. It can avoid the extra layer of a child-focused service, especially for a family that already uses a bank’s parental or joint-account tools. The downside is that a standard bank experience may feel too broad or too adult for a beginner who needs a narrower learning environment.
Till makes the most sense in the middle: a child or young teenager who needs a real spending experience but still benefits from a parent-centered structure. I would skip it for a child who is not ready to understand that card payments use real money, or for a parent who wants completely hands-off management. I would also compare alternatives carefully if the household already has a trusted bank product with controls that meet its needs and avoids an additional service.
The free installation is helpful for exploring the basic experience, but I would not choose it solely because the download costs nothing. The listed in-app purchase range means the family should examine the plan or feature being selected before committing. A useful rule is to calculate the total cost over the period you expect to use the service, then compare that with a bank-based alternative. Convenience is worthwhile only when the controls and learning value justify it.
Everyday workflow I would recommend
For a first week, I would keep the routine simple. The parent sets a clear spending purpose, the child makes one or two ordinary purchases, and both review what happened without turning the conversation into an interrogation. The child should be able to say how much was available before spending, what the purchase was meant to accomplish, and what remains for the next decision.
During the second stage, I would introduce a planned choice. Give the child a small goal, such as saving part of the available money for a later activity, while allowing the rest for immediate spending. This reveals whether the app is helping the child think ahead or merely displaying a balance. The lesson is in the trade-off: buying something now means giving up another option later.
A particularly useful workflow is to ask the child to check the balance before leaving home, not at the checkout. That tiny habit reduces surprises and makes the card feel like a responsibility rather than a magic object. If the child is shopping online, I would add another pause: confirm the merchant, the total, and whether the purchase was actually part of the agreed plan before entering payment details.
For parents, I recommend reviewing the account at a regular time rather than reacting only when something goes wrong. Look for patterns such as repeated small purchases, spending immediately after receiving money, or avoiding necessary items because the balance was used earlier. These patterns are more instructive than any single transaction. They can lead to a conversation about priorities without requiring the parent to micromanage every decision.
Where the experience may create friction
The biggest potential friction is that a supervised card still requires active parenting. If the adult does not explain the rules, review spending, or respond consistently, the child may not understand what the app is meant to teach. Families looking for an automatic allowance machine may find the setup and ongoing conversations more demanding than expected.
There is also a psychological trade-off. A child may appreciate the independence of having a card, but constant oversight can make the experience feel like surveillance. The answer is to agree in advance on what the parent will review and when. I would avoid checking every purchase instantly unless there is a genuine safety reason. Clear boundaries can provide independence inside the boundary, which is healthier than unpredictable monitoring.
Another limitation is scope. Till is not the right tool if your main goal is investing, detailed household budgeting, credit building, or adult financial planning. Its value is concentrated in supervised spending practice. Choosing it for a purpose outside that area would create disappointment, even if the app works well within its intended role.
Families should also consider the child’s maturity rather than relying only on age. The Everyone rating describes the app’s content suitability, not whether every child is ready for financial responsibility. A responsible younger user may handle a limited routine well, while an older teenager may need a more advanced account and fewer restrictions. The parent’s judgment should lead the decision.
My cautious verdict
I see Till as a focused bridge between pocket money and independent banking. Its best quality is the way a card and app can turn ordinary spending into a shared learning experience. For a parent who wants to introduce controlled freedom, track the conversation around money, and give a child practice before adult financial decisions arrive, it is worth investigating.
I would approach it with two checks. First, review the account controls, privacy explanations, permissions, and purchase choices carefully during setup. Second, decide how the family will use the app before the first transaction. Those steps protect user agency: the adult knows what is being accepted, and the child knows what the card means.
The app is less suitable for hands-off parents, children who are not ready to connect purchases with limited funds, or households that already have a bank account with better-fitting controls. It also should not be mistaken for a complete financial education program. Still, when used deliberately, Till can make money lessons concrete without immediately exposing a young person to the full complexity of adult banking.
My recommendation is cautious but positive. I would try it for a defined purpose, begin with modest responsibility, and review the experience with the child rather than assuming the app will teach everything automatically. The current Android version is 162.41.0, and the service has been available since April 27, 2022, giving families a reasonably established product to examine. For the right household, the real benefit is not simply access to a debit card; it is the chance to practice making spending decisions while a trusted adult is still close enough to guide them.


